Home Buying • Real Estate Market • Real Estate Tips • July 31, 2026

Real Estate Taxes Cincinnati and Northern Kentucky

A home’s list price is only part of its monthly and long-term cost. Buyers need to consider the big, bad, ugly word: taxes! Whether in Cincinnati or Northern Kentucky, it is important to compare real estate taxes; that number can make a home that looks affordable on paper feel very different once the full budget comes into view.

Depending on which side of the river you choose, property taxes are one of the easiest costs to underestimate. The rules, billing practices, exemptions, and local tax districts differ between Ohio and Kentucky. A smart comparison looks beyond the county line and focuses on the specific address, not just the advertised tax amount.
Real Estate Taxes and Your Home Mortgage Amount in Northern Kentucky

Why house taxes vary from one neighborhood to another

Property taxes help fund local services, including schools, fire protection, libraries, parks, and other public needs. Your bill is generally based on the property’s assessed value and the combined tax rates set by the jurisdictions serving that address.

That means two homes with similar prices can have very different house taxes. A home may be located in a city, school district, special taxing district, or fire district with rates that differ from a nearby neighborhood. This is especially common in the Tri-State, where crossing from one municipality or county to another can change the tax picture quickly.

The previous owner’s tax bill is useful, but it is not a guarantee of what a new owner will pay. A sale can lead to a valuation review, and future levy changes, reassessments, or expiring credits may affect the bill over time.

Cincinnati real estate taxes: what Ohio buyers should know

In Cincinnati and throughout Hamilton County, real estate taxes reflect county valuations and the levies approved for the property’s local taxing districts. Cincinnati addresses can also vary based on school district boundaries and other local factors, so it is wise to review the tax information for the exact property rather than estimate from a citywide average.
Cincinnati Real Estate Taxes

Ohio homeowners may qualify for programs such as the owner-occupancy credit or the homestead exemption, depending on eligibility and current rules. These benefits are not automatic in every situation, and eligibility can depend on how the property is owned and occupied. If a property has a reduced tax bill due to an exemption, buyers should confirm whether they can continue receiving it after closing.

Ohio tax values are also not set permanently. County appraisal and update cycles, along with voter-approved levies, can affect future bills even if no major improvement is made to the home.

Northern Kentucky real estate taxes: the local details matter

Northern Kentucky real estate taxes are typically assessed by the county Property Valuation Administrator, often called the PVA. Boone, Campbell, and Kenton counties each have their own assessment and billing processes; therefore, the total bill may include taxes for the county, school district, city, library, and other applicable districts.

A home in an incorporated city may have a different tax structure than one in an unincorporated part of the same county. School district lines also matter. For example, two homes a few minutes apart may fall under different districts and carry noticeably different annual property taxes.
Kentucky Real Estate Taxes, Tax Rates on Homes in Northern Kentucky

Kentucky offers a homestead exemption for qualifying homeowners, generally tied to age or disability requirements and primary residence status. It can provide meaningful savings, but a buyer should not assume the seller’s exemption transfers with the property. It usually requires the new owner to qualify and apply.

How to compare real estate taxes before making an offer

Start with the annual property tax amount shown in the listing, then ask what is included and whether an owner exemption appears to be reflected. Next, compare the tax bill with the home’s purchase price, insurance estimate, utilities, HOA dues if applicable, and expected maintenance. Looking at the full monthly cost is far more useful than focusing on the mortgage payment alone.

Buyers should also remember that taxes are commonly prorated at closing. Depending on the local contract and closing date, the seller may credit or pay their share of the current tax period. This is a closing adjustment, not a prediction of your future tax bill.

For sellers, accurate tax information helps buyers evaluate the property with confidence. Providing the most recent bill and being clear about any exemptions, pending assessments, or special circumstances can prevent surprises later in the transaction.

A better way to budget for your next move

There is no simple rule that says Ohio or Kentucky always has lower property taxes. The right answer depends on the home, its assessed value, the local district rates, available exemptions, and the services that matter most to your household.

Before you fall in love with a home, take a few minutes to review its tax history and calculate the complete ownership cost. A personalized property-by-property comparison can help you make a confident decision while keeping your move and your budget on solid ground.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080
 

Real Estate Market • July 30, 2026

Executive Neighborhoods in Northern Kentucky

Searches for “executive neighborhood northern kentucky” usually begin with a wish list: more space, a polished setting, a convenient commute, and a home that fits the next stage of life. But the right choice is rarely just about a larger floor plan or an impressive front elevation. It is about how the neighborhood supports your everyday routine, your long-term goals, and the kind of move you want to make.

What “Executive Neighborhood” Really Means

“Executive neighborhood” is not an official real estate designation. It is commonly used to describe established or newer communities with larger homes, appealing streetscapes, well-kept properties, and locations that appeal to professionals, growing families, and move-up buyers. Depending on the neighborhood, that may mean custom homes on generous lots, newer construction with modern layouts, or a well-established area with mature trees and a strong sense of community.

The label alone should not make the decision for you. Two homes with similar prices can offer very different experiences. One may provide a shorter commute and walkable surroundings, while another may offer more privacy, a newer build, and additional space for entertaining or working from home. The best fit comes down to your priorities, not just the description in a listing.

Executive Neighborhoods in Northern Kentucky Offer Different Lifestyles

Northern Kentucky gives buyers a wide range of options within reach of Cincinnati, major employers, airports, schools, parks, and local amenities. Communities such as Fort Thomas, Villa Hills, Fort Mitchell, Crestview Hills, Union, and parts of Boone County can each appeal to buyers seeking an elevated home and neighborhood experience, but they do not feel the same.

Fort Thomas often attracts buyers who value established homes, mature trees, a strong community identity, and proximity to downtown Cincinnati. Villa Hills and Fort Mitchell can offer a more residential feel with convenient access to shopping, dining, and major roadways. Crestview Hills places buyers near a central mix of amenities, while Union and other growing areas in Boone County may provide opportunities for newer construction, larger lots, and more square footage for the investment.

Availability changes quickly, and every subdivision has its own personality. Some neighborhoods have homeowners association fees and community amenities. Others offer more independence, but may have fewer shared features. Looking beyond the city name and into the specific street, lot, and surrounding homes is where a well-informed search starts to pay off.

Compare the Details That Shape Daily Life

When touring homes, it helps to look past the finishes that first catch your eye. A beautiful kitchen matters, but so do the practical details that affect daily living. Consider the drive to work at the times you would actually travel, the distance to groceries and activities, the amount of yard maintenance you want, and whether the layout works for your household now and a few years from now.

Pay attention to lot placement, too. A corner lot, cul-de-sac location, backing to green space, or proximity to a main road can change both privacy and resale appeal. If you enjoy entertaining, think about the flow between the kitchen, living areas, patio, and yard. If your workday includes remote meetings, a dedicated office or quiet flex room may be more valuable than a formal dining room.

For buyers with children, school options and transportation routines may play a major role. For downsizers, a first-floor primary suite, fewer steps, and manageable outdoor space may matter more. There is no universal definition of the perfect executive home, which is why a personalized search is so valuable.

Look Closely at Home Quality and Future Costs

Larger homes can bring larger responsibilities. Before making an offer, consider the age and condition of major systems, including the roof, HVAC, windows, appliances, and exterior features. A home inspection is essential, but it is also wise to think about ongoing costs such as utilities, property taxes, insurance, landscaping, and association fees.

Newer construction may reduce immediate maintenance needs, though buyers should still review builder warranties, lot drainage, finishes, and what remains to be completed in the surrounding development. Established homes can offer character, larger trees, and desirable locations, but may need updates that should be reflected in your budget and offer strategy.

Think About Resale Before You Need It

Even if you expect to stay for many years, resale value deserves a place in the conversation. Homes tend to remain appealing when they have functional layouts, well-maintained exteriors, practical bedroom and bathroom counts, and locations that make everyday life easier. Overly personalized renovations or a home that is significantly larger or more expensive than nearby properties can narrow the future buyer pool.

That does not mean you should buy a home only for the next owner. It means choosing a property that balances your personal needs with sound local market awareness. The goal is to feel confident about the purchase without losing sight of the investment.

A thoughtful conversation about your budget, preferred locations, commute, and must-have features can narrow the search quickly. The right executive neighborhood in Northern Kentucky should feel like more than an upgrade on paper. It should be a place that makes the next chapter of your life work better every day.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family.  Advising You Like a Professional. 859-640-6080
 

Home Selling • Real Estate Tips • July 27, 2026

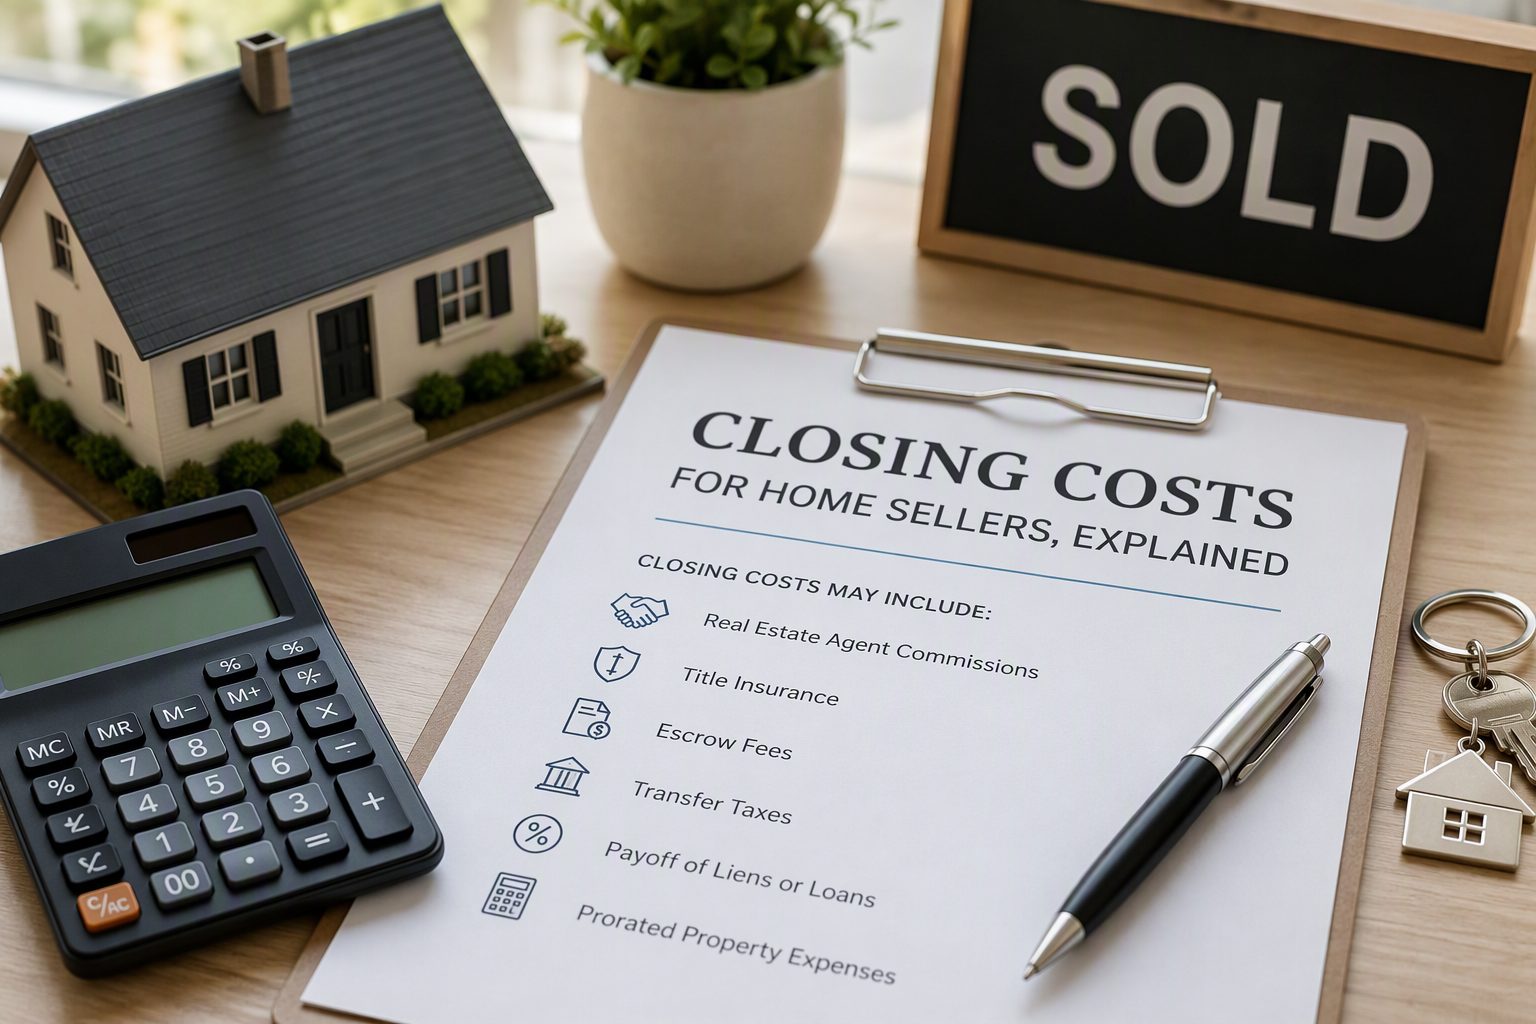
Closing Costs for Home Sellers, Explained

The number that matters most when you sell is not always the sale price. It is the amount you take home after the mortgage is paid off and the expenses of the transaction are settled. Understanding closing costs for home sellers early gives you a clearer picture of what your move can realistically fund, whether that means a down payment on your next home, a move-up purchase, or the next chapter for your family.

For homeowners, closing costs are not one fixed number. They depend on your home’s price, your loan payoff, the terms you negotiate with the buyer, and the condition of the property. A good listing strategy starts with a net-proceeds estimate, not just a suggested asking price.

What are closing costs for home sellers?

Seller closing costs are the fees, credits, and financial obligations paid from your sale proceeds at or before closing. Some are predictable, such as real estate compensation and the deed transfer tax. Others can change based on inspection findings, buyer negotiations, title issues, or the timing of your sale.

A common planning range is roughly 6% to 10% of the home’s sale price, but that number should be treated as a starting point rather than a promise. Real estate compensation is negotiated, seller concessions vary by transaction, and a home with a large mortgage balance or needed repairs can produce a very different final number than a similar home down the street.

The most useful question is not, “What percentage will I pay?” It is, “What will my estimated net proceeds be if we sell at this price and agree to these terms?” That is the calculation that helps you make decisions with confidence.

The largest costs sellers should expect

Real estate compensation

For most sellers, real estate compensation is the largest closing expense. The listing broker’s compensation is negotiated before your home goes on the market and is spelled out in the listing agreement. Depending on the offer and current market practices, a seller may also choose to offer compensation to a buyer’s agent, but that is negotiable and not automatic.

This is an area where the lowest number is not always the best value. Effective pricing, professional marketing, careful offer review, and strong negotiation can have a meaningful impact on both your final sale price and the terms you accept. The goal is not simply to get a home under contract. It is to get to the closing table with a solid buyer, manageable contingencies, and a result that supports your next move.

Mortgage payoff, liens, and prorated expenses

If you still have a mortgage, your lender will provide a payoff amount that must be paid from the sale proceeds. That figure is often slightly higher than the balance you see on your monthly statement because it includes interest through the payoff date and, in some cases, a small payoff or processing fee.

Other obligations tied to the property may also need to be resolved. These can include a home equity line of credit, unpaid contractor liens, judgments, or delinquent HOA dues. A title search is designed to identify issues that need attention before ownership can transfer.

Property taxes, HOA fees, and certain utilities may be prorated based on the closing date and local billing schedules. In Northern Kentucky, the title company and contract terms will determine the proper adjustments. These line items are often modest compared with a mortgage payoff, but they still affect the bottom-line number.

Kentucky deed transfer tax and title-related charges

Kentucky charges a deed transfer tax when real estate changes hands. It is generally calculated at 50 cents per $500 of the property’s value, or 0.1% of the sale price. On a $300,000 sale, that would be about $300. The seller commonly pays this expense, although terms can always be negotiated in the purchase contract.

Sellers may also see title-related charges, such as fees for releasing an existing mortgage, recording documents, obtaining payoff information, or handling the closing. Who pays for an owner’s title insurance policy can vary by local custom and by the terms of the agreement. Never assume a cost is automatically yours or the buyer’s without reviewing the offer carefully.

Repairs, inspection requests, and buyer credits

Not every cost appears on the first estimate. After an inspection, a buyer may ask for repairs, a price reduction, or a credit at closing. A seller is not required to agree to every request, but ignoring legitimate health, safety, or financing concerns can put an otherwise strong contract at risk.

Credits can be especially useful when a repair is inconvenient to complete before closing or when the buyer prefers to handle the work after moving in. Still, credits reduce your proceeds dollar for dollar. The right response depends on the repair, the buyer’s financing, the strength of backup interest, and whether the request is likely to come up again with another buyer.

For example, an aging water heater may be something a buyer can accept as-is. An active roof leak or electrical safety issue is more likely to affect an appraisal, a lender’s requirements, or the next buyer’s inspection. A thoughtful negotiation looks at the whole offer, not just one repair request in isolation.

Seller concessions: a strategic cost, not always a loss

A seller concession is a contribution toward a buyer’s eligible closing costs, prepaid items, or other costs allowed by the buyer’s loan program. It can make an offer more attractive, particularly for first-time buyers who have the income to qualify but need help with the cash required to close.

That does not mean sellers should offer concessions automatically. In a competitive situation, a buyer may not need one. In a slower price range or when a home needs updating, a concession can help expand the buyer pool and preserve the sale price. Sometimes a $5,000 credit paired with a stronger price and cleaner terms is better than accepting a lower-price offer with no credit.

The key is to look at the net result. Two offers with the same purchase price can leave you with very different proceeds once concessions, repair requests, financing terms, and closing timelines are considered.

Costs that can surprise sellers

A few expenses are easy to overlook until a transaction is underway. If you are selling a condo or a home in a homeowners association, there may be document fees, resale certificate fees, transfer charges, or unpaid assessments. Some communities also require a final inspection or approval process before closing.

If your property is vacant, you may need to maintain insurance, utilities, lawn care, or snow removal through closing. If you are moving before the sale is complete, storage and temporary housing should be part of your personal moving budget, even though they do not appear on the settlement statement.

Homes with older additions, inherited ownership, boundary questions, or previous lien issues can require extra time and paperwork. None of these situations means a sale cannot happen. They simply make early preparation more valuable.

How to estimate your net proceeds before listing

Before putting a sign in the yard, ask for a seller net sheet based on a realistic price range. It should estimate the mortgage payoff, negotiated real estate compensation, transfer tax, title and closing charges, likely prorations, and a reasonable allowance for possible concessions or repairs.

It is wise to review more than one scenario. Consider what happens if the home sells at your target price, slightly below it, or with a buyer credit. If you are buying another home at the same time, compare those estimates with the cash you will need for your next purchase. This is especially helpful for families coordinating a sale and purchase on a tight timeline.

A net sheet is an estimate, not a replacement for the final settlement statement. Your exact figures will be confirmed by the title company, lender, and closing documents. But an early estimate helps prevent the disappointment of discovering that a strong sale price does not translate into the proceeds you expected.

Ways to keep seller costs under control

The best way to manage selling expenses is not to cut every cost. It is to make decisions early enough that you have options. Addressing obvious maintenance items before listing can reduce last-minute repair negotiations. Pricing accurately can limit repeated price reductions and help attract buyers who are prepared to act.

It also helps to review every offer beyond the headline number. A slightly lower offer with a larger down payment, fewer contingencies, and no request for credits may be financially stronger than a higher offer with multiple demands. Your timing matters, too. A flexible closing date can sometimes be worth more to a buyer than an additional concession.

Selling a home involves more than preparing rooms for photos. It means preparing for the financial handoff as well. When you understand your costs before the first showing, you can evaluate offers calmly and make choices that keep your next move within reach.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080
 

Real Estate Tips • Understanding Real Estate Terms • July 26, 2026

Seller Disclosure Questions Answered for Home Sellers

A buyer standing in your kitchen may love the hardwood floors, the backyard, and the school district. But before they commit, they will also want to know what has happened behind the walls, under the roof, and around the property. That is where seller disclosure questions answered clearly and honestly can protect both your transaction and your peace of mind.

For Northern Kentucky homeowners, the disclosure form is not just another piece of closing paperwork. It is an opportunity to give buyers a straightforward picture of the property based on what you know. A well-handled disclosure builds trust, reduces surprises during inspections, and helps keep a sale moving forward.

What is a seller disclosure?

In Kentucky, most residential sellers complete a Seller’s Disclosure of Property Condition form. The form asks about your knowledge of the home’s condition, including the roof, foundation, plumbing, electrical systems, heating and cooling, appliances, water issues, environmental concerns, and more.

The key word is knowledge. Sellers are generally expected to disclose known material defects or conditions that could affect a buyer’s decision or the property’s value. You are not expected to be a home inspector, engineer, or contractor. If you do not know the answer to a question, do not guess. State that you do not know, and let the buyer complete their own inspections.

This is also why disclosure forms are not a replacement for an inspection. Buyers should still hire qualified professionals to evaluate the home, even when a seller has maintained the property carefully and answered every question in good faith.

Seller disclosure questions answered: what should you report?

A practical rule is simple: if you know about a condition that could reasonably matter to a buyer, disclose it. A past basement leak, a repaired roof issue, an aging HVAC system, or a recurring drainage concern may not stop a sale. Hiding or minimizing it, however, can create far bigger problems later.

Do I have to disclose past repairs?

Usually, yes, when the repair relates to a significant issue or a condition addressed on the disclosure form. For example, if water entered the basement during a heavy storm and you installed a drainage solution, it is wise to explain what occurred and what was done to correct it.

A repair can actually reassure a buyer when it is documented. Keep receipts, warranties, contractor invoices, permits, and before-and-after information when available. Saying, “The roof was replaced in 2022 by a licensed contractor,” gives a buyer much more confidence than a vague statement that the roof was “fixed.”

The same applies to foundation work, sewer repairs, electrical updates, mold remediation, and major appliance replacements. Share the facts without trying to diagnose the issue beyond your expertise.

What if the problem is no longer happening?

A condition that seems resolved can still be relevant. If your sump pump failed once but was replaced, or if you had a plumbing leak that was professionally repaired, disclose the history and the repair. Buyers may ask follow-up questions, but they are often more comfortable when they see that an issue was handled responsibly.

It depends on the situation, of course. A minor cosmetic repair from years ago is different from a recurring water intrusion issue. When there is any doubt about whether something belongs on the form, it is usually better to discuss it before listing than to leave a buyer wondering why it was omitted.

What if I never lived in the home?

This comes up often with inherited homes, rental properties, and investment properties. You should still complete the disclosure form based on the information you have. If you do not have personal knowledge of a system or condition, say so rather than checking a box that suggests certainty.

For a rental home, records from maintenance requests, property managers, contractors, and tenants may help you answer accurately. For an inherited property, family records and recent repair invoices can be useful. Buyers may take a more cautious approach when a seller has limited knowledge, which makes thorough inspections especially valuable.

Should I disclose neighborhood or location concerns?

The disclosure form focuses primarily on the property itself, but location-related facts can matter. For instance, a shared driveway arrangement, an easement, a known boundary dispute, frequent flooding on the lot, or a planned change that directly affects the property may warrant discussion.

Northern Kentucky has a mix of older neighborhoods, hillside properties, river-adjacent areas, and newer subdivisions. Drainage, retaining walls, septic systems, shared access, and past mining or soil conditions can vary from one area to another. Local knowledge matters because the right questions for a historic Covington home may differ from those for a newer home in Boone, Kenton, or Campbell County.

How detailed should your answers be?

Be specific enough to be useful, but do not write a long story that creates confusion. Dates, locations, repairs, and supporting documentation are more helpful than broad phrases such as “minor issue” or “normal wear.”

For example, instead of writing, “Basement had water,” a clearer response might say: “Water entered the rear corner of the unfinished basement during heavy rainfall in April 2023. A contractor installed an exterior drain extension and sealed the area. No water has been observed since the repair.”

That response does not promise that water can never return. It simply gives the buyer an honest account of what you know and what action you took.

Avoid checking “no” when the real answer is “yes, but it was repaired.” Also avoid assuming that a buyer will discover something during inspection, so you do not need to mention it. Inspections can uncover a lot, but disclosure and inspection serve different purposes. A buyer should not have to piece together a property’s history after the fact.

Can a disclosure hurt my home sale?

Sellers often worry that disclosure will make buyers walk away or force a major price reduction. Sometimes a significant condition does affect value or negotiation, especially if a repair is still needed. But a surprise discovered late in the process can be more disruptive than an issue disclosed early.

A known concern gives you choices. You may decide to repair it before listing, price the home with the condition in mind, offer documentation that shows the issue was addressed, or wait to see what the buyer’s inspection reveals. There is no one right answer for every property.

For example, replacing a roof before listing may make sense if it is at the end of its useful life and likely to affect financing or insurance. On the other hand, a seller may choose not to replace an older but functioning HVAC system and instead set realistic expectations through price and disclosure. The best approach depends on your budget, timeline, current market conditions, and the condition of comparable homes nearby.

When should you complete the disclosure form?

Complete it before the home goes active whenever possible. That gives you time to locate records, confirm dates, and think through questions without the pressure of an offer deadline. It also allows potential buyers to review the property information early, which can lead to more informed offers.

If something changes after you complete the form, update it. A new leak, appliance failure, insurance claim, or repair should not be ignored simply because the original form has already been signed. Keeping the disclosure current is part of keeping the transaction transparent.

A smart way to prepare before listing

Before filling out the form, gather your home records in one place. Look for roof and HVAC invoices, warranty information, repair receipts, permits, utility information, septic or well records if applicable, and insurance documentation for past claims. You do not need a perfect file for every small project, but organized records make accurate answers easier.

Then walk through the home with a seller’s mindset. Think about the questions a careful buyer may ask: Has the basement ever leaked? Are there cracks that have changed over time? When were major systems serviced? Has an appliance had a recurring issue? Is there anything about the lot, driveway, fence, or shared access that a new owner should understand?

A trusted real estate professional can help you approach these questions thoughtfully and identify areas where additional documentation or professional advice may be worthwhile. For legal questions or a difficult disclosure situation, an attorney is the right resource for advice tailored to your circumstances.

Honesty on a disclosure form is not about making a home sound imperfect. Every home has a history. It is about showing buyers that you have cared for the property, respected the process, and given them the information they need to make a confident next move.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080
Real Estate Tips • July 24, 2026

How Long Does It Take to Buy a House in Kentucky?

The day you find the home that feels right, it is natural to want the keys immediately. But how long does it take to buy a house? For many Northern Kentucky buyers, the answer is about 30 to 45 days from an accepted offer to closing. The full journey, from deciding you are ready to buy through moving day, is often closer to two to six months.

That range is not meant to make the process feel uncertain. It is meant to help you plan realistically. A well-prepared buyer can move quickly when the right home appears, while a buyer who needs time to improve credit, save for closing costs, or sell a current home may need a longer runway.

How Long Does It Take to Buy a House From Start to Finish?

There are really two timelines to consider: the time before you make an offer and the time after your offer is accepted. The second timeline is more predictable because it follows the terms of your purchase contract. The first depends on your finances, priorities, and the availability of homes that fit your needs.

If you are already pre-approved, know your preferred Northern Kentucky communities, and are flexible on a few nonessential features, you may find a home and get under contract within a few weeks. For others, the search takes several months. Families weighing school districts, commute times into Cincinnati, yard size, or proximity to relatives often need more time to compare neighborhoods and avoid settling too quickly.

Once your offer is accepted, a typical financed purchase generally takes 30 to 45 days to close. Cash purchases can sometimes close in two to three weeks, although title work, inspections, and scheduling still need to be handled carefully.

Before You Start Touring: Allow Two to Six Weeks

The smoothest home searches begin before the first showing. Start by reviewing your monthly budget honestly, including future expenses such as utilities, maintenance, furnishings, and any HOA fees. A lender can help determine what you may qualify to borrow, but your comfortable payment matters just as much as the maximum approval amount.

Getting pre-approved is one of the most valuable early steps. A pre-approval gives you a clearer price range and shows sellers that your financing has been reviewed. It also helps prevent a frustrating situation where you fall in love with a home only to learn it is outside your workable budget.

During this stage, buyers should also set aside funds for earnest money, inspections, appraisal-related costs when applicable, closing costs, and moving expenses. Some buyers may qualify for assistance programs, but it is wise to understand the details early rather than building a plan around funds that have not been confirmed.

Choosing an agent early can save time, too. A local agent can help you narrow the search based on how you actually live, not just the number of bedrooms on a listing. A home in Independence, Florence, Fort Thomas, Union, or Hebron may offer a very different daily routine, even when the homes appear similar online.

The Home Search Can Take Days or Months

There is no ideal number of homes to tour. Some buyers write an offer after their first weekend of showings. Others need several months to learn what matters most to them. Both experiences are normal.

The pace often comes down to three factors: inventory, competition, and decision-making. When attractive homes are limited in a particular price range or school district, you may need to act quickly when a suitable property hits the market. On the other hand, rushing into a home that does not meet your core needs can create regrets long after closing.

It helps to separate must-haves from preferences. A manageable commute, enough bedrooms, a safe layout for young children, or first-floor living may be true needs. Granite counters, a specific paint color, or a finished basement may be items you can change or compromise on. This clarity makes decisions faster when a strong option appears.

For buyers who are also selling a current home, timing requires extra coordination. You may need to sell first, buy first, negotiate a longer closing, or arrange temporary housing. There is no one right answer. The best approach depends on your finances, comfort with risk, and the pace of both your current home’s sale and your next home search.

After the Offer Is Accepted: The 30-to-45-Day Timeline

An accepted offer is a major milestone, but it is not the finish line. The weeks between contract and closing are when the lender, title company, inspectors, buyer, seller, and agents work through the details that allow ownership to transfer.

Inspections Usually Happen First

In Kentucky, buyers commonly schedule a home inspection shortly after the contract is signed. Depending on the property, additional inspections may be appropriate for radon, termites, septic systems, roofs, chimneys, or other concerns. Your inspection period is the time to understand the home’s condition and decide whether to request repairs, ask for a credit, renegotiate, or move forward as written.

Inspections do not mean a home must be perfect. Nearly every property, including newer construction, will have maintenance items. The goal is to identify material issues, safety concerns, and expenses that could affect your decision or budget.

The Loan and Appraisal Move Forward Together

After the contract, your lender begins processing the mortgage in greater detail. They may request updated pay stubs, bank statements, explanations for deposits, tax documents, or other information. Responding promptly matters. Even a small delay in sending paperwork can slow underwriting.

The lender also orders an appraisal to support the home’s value for the loan. If the appraisal comes in at or above the contract price, the transaction usually keeps moving. If it comes in low, the buyer and seller may need to renegotiate the price, adjust the loan structure, bring in additional funds, challenge the appraisal when appropriate, or agree to end the contract under the applicable contingency.

Avoid major financial changes during this period. Do not open new credit accounts, finance furniture or a vehicle, change jobs without discussing it with your lender, or move large unexplained sums between accounts. A pre-approval is a strong start, but final loan approval depends on your financial profile remaining consistent.

Title Work and Final Details Take Time

A title company researches the property’s ownership history and works to make sure the title can be transferred appropriately. They also prepare closing documents, coordinate payoff information when needed, and help organize the final transfer of funds.

Meanwhile, your agent tracks deadlines, communicates with the other side, and helps keep small questions from becoming larger problems. A final walk-through usually happens shortly before closing. It is your chance to confirm that the home is in substantially the agreed-upon condition, requested repairs have been addressed, and included items remain at the property.

What Can Delay a Home Closing?

Most closings happen on schedule, but delays are possible. Financing documentation is one common reason, especially when buyers are self-employed, have variable income, or need to explain deposits and credit changes. Appraisal issues, inspection negotiations, title questions, repair scheduling, and a seller’s delayed move can also affect the closing date.

A delay does not automatically mean the deal is falling apart. Often, it means one party needs a few more days to provide documents, complete a repair, or resolve a detail. Clear communication and realistic expectations make these moments much easier to manage.

Buyers can protect their timeline by keeping documents organized, reviewing contract deadlines closely, scheduling inspections quickly, and staying available for lender questions. Your agent cannot control every moving part, but they can help you anticipate them and keep the transaction moving forward.

A Better Goal Than a Fast Closing

The fastest possible purchase is not always the best purchase. A quick timeline can be helpful when a lease is ending, a job relocation is approaching, or you need to sell and buy within a narrow window. But confidence comes from being prepared, understanding each deadline, and having the right people in your corner.

Whether your search takes two weeks or several months, the right home should support the next chapter of your life, not simply meet a deadline. Start your planning early, leave room for the unexpected, and give yourself permission to make a thoughtful decision when the right Northern Kentucky home comes along.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080
Real Estate Tips • July 23, 2026

A Buying After Renting Guide for Northern Kentucky

The moment a lease renewal arrives, many renters start doing the same math: another year of rent, another move, or a chance to build something of their own. This buying after renting guide is designed for Northern Kentucky renters who are ready to explore homeownership without rushing into a decision that does not fit their life, budget, or plans.

Buying a home can feel like a major shift because it is one. You are taking on more responsibility, but you are also gaining more control over where and how you live. The goal is not simply to stop renting. It is to buy a home that supports your next chapter with confidence.

Start With the Question Behind the Move

The first question is not, “What can I afford?” It is, “Why do I want to buy now?” Maybe you want room for a growing family, a backyard for a dog, a shorter commute to Cincinnati, or the freedom to paint the walls without asking permission. Maybe your rent has increased enough that a mortgage payment is beginning to look more appealing.

Your reason matters because it helps shape the right search. A buyer who expects to stay put for several years may prioritize a neighborhood and long-term value. Someone who may relocate soon for work needs to think more carefully about flexibility, resale potential, and the costs of buying and selling within a short period.

There is no universal timeline that makes renting or buying automatically better. Homeownership tends to make the most sense when you have stable income, enough savings, and a reasonable expectation that you will stay in the area long enough to benefit from the move.

Get Clear on the Full Cost of Owning

Renters are used to one predictable monthly payment, even if utilities vary. Homeownership has more moving pieces. Your mortgage payment may include principal, interest, property taxes, and homeowners insurance. Depending on the property and loan type, it may also include private mortgage insurance or homeowners association dues.

Then there are the expenses that do not show up in a listing price. A water heater eventually needs attention. Gutters need cleaning. A moving truck, window coverings, lawn equipment, and a few unexpected repairs can add up quickly during the first year.

That does not mean you need a perfect house fund before you start looking. It does mean you should leave room in your budget after the down payment and closing costs. A home should feel like a foundation for your life, not a payment that makes every other decision stressful.

A lender can help you understand how much you may be approved to borrow, but approval is not the same as comfort. Look at your actual monthly spending, savings goals, childcare costs, student loans, car payments, and the lifestyle you want to maintain. The right price range is the one that lets you own a home and still breathe.

Down Payment Myths Can Delay Good Decisions

Many first-time buyers assume they need 20 percent down before they can even talk with a lender. In some cases, putting 20 percent down may be a smart strategy. It can lower the loan amount and may eliminate private mortgage insurance. But it is not the only path to ownership.

Loan programs can allow qualified buyers to purchase with less money down, and some buyers may have access to down payment assistance programs. The details depend on credit, income, loan type, property type, and current program guidelines. A conversation with a trusted local lender gives you real numbers instead of internet assumptions.

Keep your emergency savings in the conversation. Draining every available dollar for a larger down payment can leave a new homeowner exposed when normal home expenses arise.

Prepare Before You Fall for a House

A little preparation makes the search less emotional and puts you in a stronger position when the right home appears. Before touring seriously, review your credit report, avoid taking on new debt, and gather documents a lender is likely to request, including pay stubs, tax returns, bank statements, and employment information.

Preapproval is especially valuable in a competitive market. It gives you a clearer budget and shows sellers that you have taken the financial side seriously. Prequalification can be a useful early estimate, but preapproval generally involves a more complete review of your finances.

Try not to make major financial changes while you are under contract. Opening a new credit card, financing furniture, changing jobs, or moving large unexplained deposits between accounts can create extra questions for your lender. Even exciting purchases can wait until after closing.

Use a Buying After Renting Guide to Set Priorities

Renting often teaches people exactly what they do and do not want. Perhaps you are tired of hearing upstairs neighbors, carrying groceries upstairs, or having no place to store holiday decorations. Those frustrations are useful information, but they should be turned into clear priorities before your search begins.

Separate your needs from your wants. Needs might include the number of bedrooms, a first-floor primary bedroom, a manageable commute, or a school district that works for your family. Wants may include a finished basement, a certain style of kitchen, or a large deck. Both matter, but knowing the difference helps when trade-offs appear.

Northern Kentucky offers a wide range of choices, from established neighborhoods in Fort Thomas and Villa Hills to convenient communities in Florence, Independence, Alexandria, and beyond. A home closer to downtown Cincinnati may offer a shorter commute and a more walkable setting. A home farther out may offer more space or a different price point. Neither option is automatically better. It depends on how you spend your weekdays, weekends, and future plans.

When evaluating a neighborhood, pay attention to more than the house itself. Drive the route at the times you would normally travel. Notice traffic patterns, nearby amenities, lot sizes, noise, parking, and the overall upkeep of surrounding homes. A home can be updated beautifully, but the location will influence your day-to-day experience and future resale.

Understand What Happens After an Offer Is Accepted

Getting an offer accepted is exciting, but it is not the finish line. The contract period is where careful guidance matters most. Your purchase agreement will establish timelines and contingencies, including financing, inspections, appraisal, and closing.

A home inspection is not a pass-fail test. It is an opportunity to understand the property. Nearly every home, including newer ones, will have findings. The important question is whether those findings involve safety, major systems, significant repairs, or items you are comfortable handling over time.

The appraisal serves a different purpose. It helps the lender confirm that the home supports the agreed-upon value. If the appraisal comes in below the contract price, there may be options to renegotiate, adjust financing, challenge the appraisal with relevant information, or bring additional funds to closing. The right response depends on the contract, the market, and your financial comfort level.

This part of the process can feel like a lot when you are moving from a rental, where maintenance and paperwork were usually someone else’s responsibility. That is why having responsive professionals around you matters. Your agent, lender, inspector, title team, and insurance provider should help you understand what is happening rather than simply telling you where to sign.

Plan the Move Without Creating Unnecessary Stress

Once closing approaches, renters have a practical challenge homeowners do not always think about: coordinating notice to a landlord, a lease end date, moving day, and utility transfers. Review your lease early. Understand notice requirements, possible early termination terms, and any conditions for receiving your security deposit back.

If possible, avoid scheduling your move so tightly that one small delay creates a crisis. Closing dates can shift. Having a backup plan for a few days of overlap, storage, or temporary lodging can be worth the added cost for peace of mind.

Before turning in your rental keys, document the condition of the unit with photos and complete any required cleaning or repair steps. It is one more detail, but recovering your deposit can help offset moving expenses or your first few home projects.

Buy the Home That Works for Your Real Life

The best first home is not always the largest home, the newest home, or the home with every feature on a social media wish list. It is the one that meets your core needs, fits your financial picture, and gives you a place to grow without stretching beyond what feels responsible.

For renters throughout Northern Kentucky and the Cincinnati Tri-State area, buying can be both exciting and intimidating. A personalized conversation can turn broad questions into a practical plan, from choosing a price range to narrowing neighborhoods and preparing a competitive offer. When you are ready, the next step is not pressure to buy. It is simply getting clear on what a confident move forward looks like for you.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080
Real Estate Market • July 22, 2026

Should I Rent or Buy in Northern Kentucky?

A lease renewal, a growing family, a new job, or a rent increase can bring one big question into focus: should I rent or buy? For Northern Kentucky residents and those relocating from across the Cincinnati Tri-State, the answer is rarely as simple as comparing a monthly rent payment with a mortgage payment. The right choice depends on your timeline, your finances, your lifestyle, and what you want the next few years to look like.

Buying a home can create stability and a sense of ownership. Renting can offer flexibility and fewer responsibilities. Neither option is automatically better. The goal is to choose the one that supports your life now without putting unnecessary pressure on your future.

Should I Rent or Buy? Start With Your Timeline

Your expected length of stay is one of the clearest factors in the rent-versus-buy decision. Buying involves upfront costs, including your down payment, closing costs, inspections, moving expenses, and the inevitable first round of updates or furnishings. When you sell, there are costs on that side as well.

Because of those expenses, buying often makes more financial sense when you expect to stay in the home for several years. There is no universal break-even number, since home price, interest rate, appreciation, and loan terms all matter. Still, if you know a job transfer, family change, or relocation could take you elsewhere in a year or two, renting may give you useful breathing room.

On the other hand, if you are settled in Northern Kentucky, want to put down roots, and can see yourself in a home for five years or longer, buying may be worth a closer look. Communities such as Fort Thomas, Florence, Independence, Union, Hebron, and Burlington each offer different housing styles, commutes, school considerations, and price points. Finding the right fit can make a longer-term purchase feel much more practical.

Look Beyond the Monthly Payment

A common mistake is assuming that a mortgage payment tells the whole story. It does not. A true homeownership budget includes principal and interest, property taxes, homeowners insurance, and potentially mortgage insurance or homeowners association fees. You also need room for maintenance, repairs, and utilities that may be higher than they were in an apartment or rental home.

A good rule of thumb is to keep an emergency fund after closing rather than using every available dollar for a down payment. A water heater does not wait for the perfect financial moment, and neither does a roof repair, appliance replacement, or plumbing issue. Homeownership brings control, but it also brings responsibility.

Renting has costs beyond the advertised rent, too. Rent can rise at renewal, and tenants may pay for utilities, parking, pet fees, renter’s insurance, and move-in fees. More significantly, rent payments do not build equity in a property you own. That does not make renting wasted money. You are paying for a place to live and for the freedom to move without taking on the financial obligations of ownership.

The better comparison is not simply rent versus mortgage. Compare your total monthly housing cost, your available savings, and the level of financial flexibility you need.

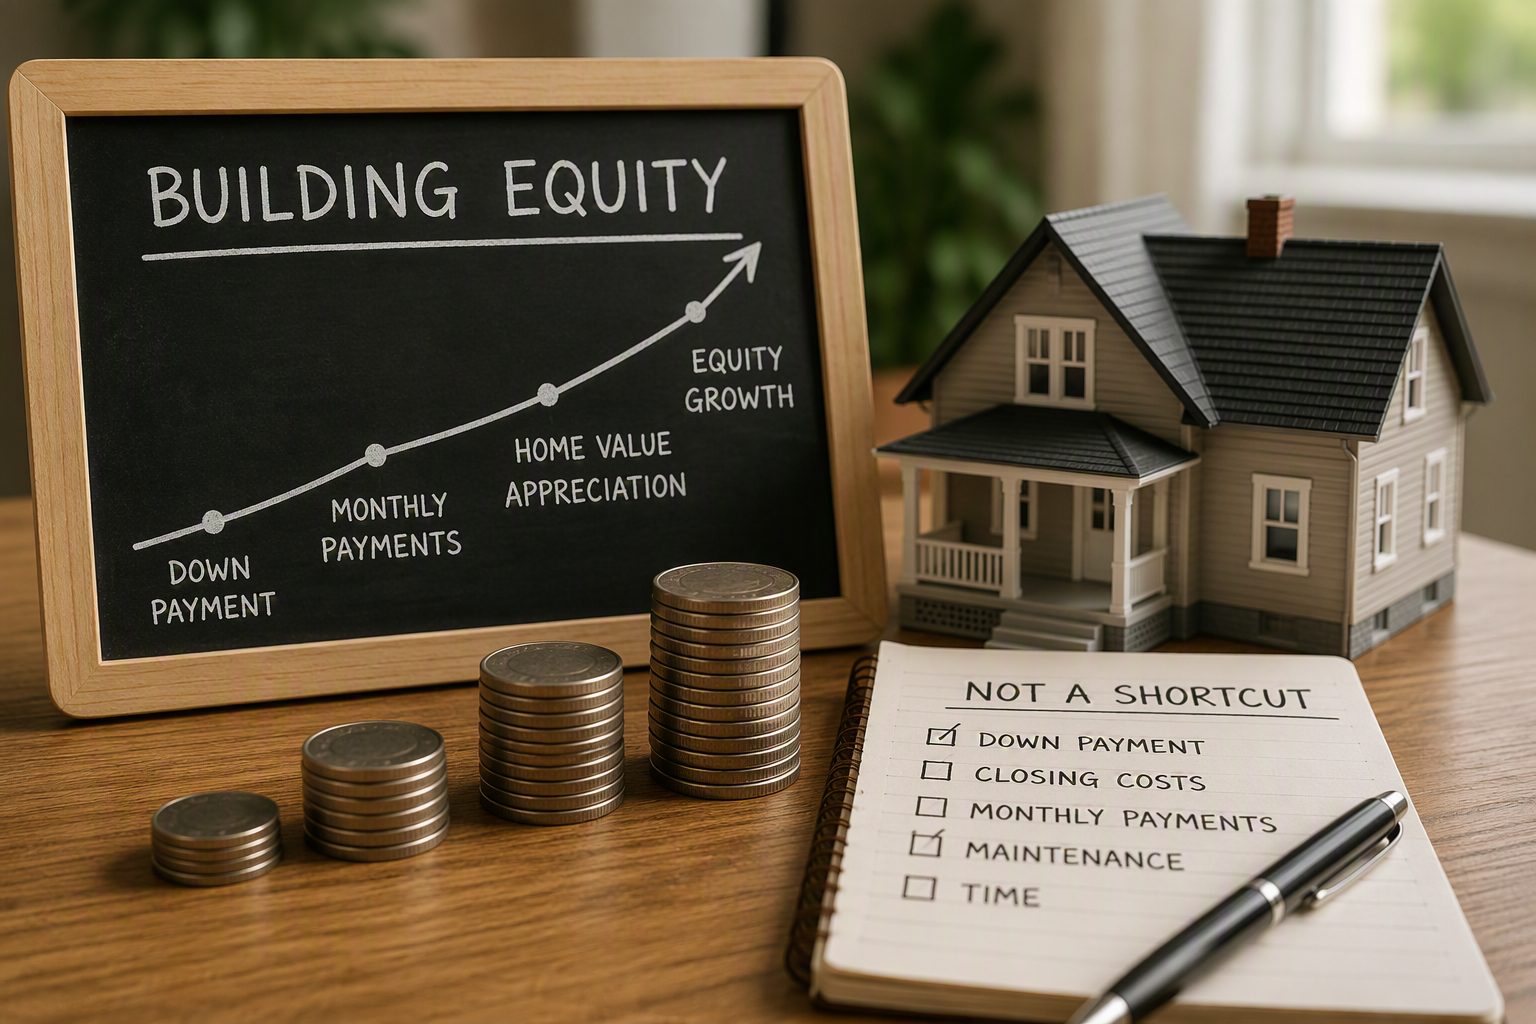
Buying Can Build Equity, But It Is Not a Shortcut

One of the strongest reasons people choose to buy is the opportunity to build equity. As you pay down your loan and, ideally, as your home’s value grows over time, you build an ownership stake that can support a later move, a downsizing plan, or long-term wealth goals.

But equity is not guaranteed on a particular schedule. Real estate values can shift, and the market may not move in a straight line. A buyer should not purchase a home based only on the expectation of a quick profit. The most reliable benefit often comes from owning a home that fits your needs over time while you make consistent payments and care for the property.

For first-time buyers, this is especially worth remembering. Your first home does not have to be your forever home. It can be a comfortable, manageable starting point that gives you more space, a yard, a preferred neighborhood, or a path toward the next stage of life.

Flexibility Has Real Value

Renting is often the better choice when flexibility matters more than permanence. Maybe you are new to the Cincinnati area and want time to learn which side of the river feels right. Maybe your commute, family plans, or work situation could change soon. Perhaps you are rebuilding savings, paying down high-interest debt, or simply do not want to spend weekends handling home projects.

A rental can give you time to explore Northern Kentucky neighborhoods before committing to one. You can learn how long a commute actually feels at rush hour, where you like to shop, which parks your family uses, and what community atmosphere feels most like home.

There is also a lifestyle component. Some people genuinely prefer having a landlord handle major repairs. Others want the freedom to paint the walls, plant a garden, adopt another dog, or renovate a kitchen without asking permission. The better choice is the one that matches how you want to live, not just what looks best on a spreadsheet.

You Do Not Need a Perfect Down Payment

Many potential buyers wait because they believe they need 20 percent down. A larger down payment can lower your monthly payment and may help you avoid private mortgage insurance, but it is not the only path to homeownership. Loan options exist for qualified buyers with lower down payments, and some programs may help with down payment or closing-cost needs.

That said, buying with a smaller down payment should still leave you financially comfortable. The goal is not simply to qualify for a loan. The goal is to own a home without feeling stretched every month.

Before deciding that buying is out of reach, it helps to speak with a trusted lender about your real numbers. A pre-approval can clarify your likely price range, estimated monthly payment, cash needed to close, and the steps that could strengthen your position if you are not ready yet. Sometimes the right answer is to buy now. Sometimes it is to make a six- or twelve-month plan and buy with more confidence later.

Consider What You Cannot Change About a Home

Paint colors, flooring, and light fixtures can be changed. Location cannot. For buyers considering Northern Kentucky, neighborhood selection deserves as much attention as the house itself.

Think about your everyday routine. How important is access to downtown Cincinnati, the airport, schools, medical care, parks, restaurants, or family members? Would you rather have an older home near established amenities, a newer home in a growing area, or a lower-maintenance townhome or condo? These questions affect both your satisfaction and the homes that fit your budget.

Renting may be a smart way to test an area before purchasing, particularly for a relocation. Yet if you already know the community and have found an area that supports your daily life, buying can provide the stability to become part of it.

A Practical Way to Make the Decision

Instead of asking whether buying is always smarter than renting, ask a few more personal questions. Can you comfortably afford the full cost of owning a home? Do you expect to remain in the area long enough for a purchase to make sense? Do you have savings beyond your closing costs? Are you ready for maintenance responsibilities? And does ownership support a goal that matters to you, such as more space, a stable school routine, a home office, or a place to gather with family?

If the answers are mostly yes, it may be time to explore your buying options. If several answers are no, renting can be a thoughtful decision, not a failure to move forward. It may be the right season to protect your flexibility and prepare for a stronger purchase later.

The best next step is not pressure to choose quickly. It is a clear conversation about your goals, budget, and timing. With local market insight and a realistic plan, you can make a housing decision that feels less intimidating and much more like a confident step toward what comes next.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080
Understanding Real Estate Terms • July 21, 2026

What Is a Contingent Offer on Home Sale?

A contingent offer on a home sale is often the bridge between the home you own and the home you hope to buy next. For many Northern Kentucky families, selling first is not simply a preference. The proceeds from that sale may provide the down payment, reduce the new mortgage payment, or make the next move financially comfortable. The challenge is that a seller considering your offer also has to weigh the uncertainty of your current home selling on time.

That does not mean a home-sale contingency is a bad idea. It means the offer needs to be structured thoughtfully, supported by realistic numbers, and communicated clearly. The right approach can protect your finances while still giving you a credible chance at the home you want.

What a Contingent Offer on Home Sale Means

A contingent offer is an offer to purchase a home that depends on a specific condition being met. With a home-sale contingency, the buyer must sell their current property before they are required to move forward with the purchase.

The contingency usually identifies the address of the buyer’s current home and sets a deadline for it to go under contract, close, or both. If the stated condition is not met by the deadline, the buyer may be able to cancel the purchase agreement and receive their earnest money back, depending on the language of the contract.

There are two common situations. In one, the buyer’s home is already under contract but has not yet closed. In the other, the buyer has not listed their home yet, or it is listed without a buyer. Sellers generally see these situations very differently.

A buyer whose home is already under contract has cleared an important hurdle, even though that sale may still include inspections, appraisal, financing, or other contingencies. A buyer who needs to list and sell their home from scratch presents more unknowns. The price, condition, marketing plan, and buyer demand for that home all affect whether the new purchase can happen.

Why Buyers Use a Home-Sale Contingency

The main benefit is financial protection. Selling your current home first helps you avoid owning two homes at once or taking on a larger payment than you intended. It can also prevent a rushed sale at a lower price just to meet the deadline for a new purchase.

For move-up buyers, this can be especially practical. A growing family may need more bedrooms, a better layout, or a different school district, but a large part of their available down payment may be tied up in their current property. Downsizers often face a similar decision: they may prefer not to use savings for a new home until they know the equity from their existing home.

A home-sale contingency also creates room for a more orderly move. Rather than moving into temporary housing, storing belongings, and moving again, a buyer may be able to coordinate both closings more closely. That convenience matters, but it should not be the only reason to use a contingency. The contract should reflect what you truly need to make a sound financial decision.

How Sellers View Contingent Offers

From a seller’s perspective, every offer is evaluated on both price and certainty. A strong price is attractive, but an offer tied to another sale introduces an additional link in the chain. If that sale falls through, the seller may lose valuable time and need to put their home back on the market.

This is why a seller may accept a lower offer from a buyer who is fully approved, has a substantial down payment, and does not need to sell another property. It is not necessarily a judgment about you or your home. It is a business decision shaped by the seller’s own timeline, finances, and confidence in competing offers.

Market conditions matter, too. In a slower market, sellers may be more open to a well-supported contingency because qualified buyers have more negotiating room. When desirable homes in Northern Kentucky receive multiple offers quickly, a seller may have less reason to accept added uncertainty. Even then, a contingent offer can succeed when it is clean, realistic, and backed by a marketable current home.

Make Your Offer More Competitive

A home-sale contingency should never be treated as a vague promise that your home will sell. Before writing an offer, understand what your current property is likely to sell for, how much you will net after mortgage payoff and closing costs, and what preparation may be needed before it goes on the market.

If possible, list your current home before making an offer on the next one. Better yet, have it under contract. This gives the seller more confidence and lets you make decisions based on a real sale price rather than an estimate. It also helps your lender provide a clearer picture of your purchasing power.

The offer terms can matter nearly as much as the contingency itself. A reasonable contingency deadline, strong pre-approval, appropriate earnest money, and flexibility around possession can all help. If your home is already under contract, providing relevant details about its status may reassure the seller, while still respecting privacy and contract obligations.

Pricing your current home correctly is one of the most important pieces. An overpriced listing can sit for weeks, placing the purchase at risk and making the contingency look less credible. A local pricing strategy should consider recent comparable sales, current competition, condition, location, and the pace of activity in your particular neighborhood. A home in Fort Thomas may attract buyers differently than one in Florence, Independence, Covington, or nearby Cincinnati communities.

Avoid trying to solve uncertainty by offering far more than a home’s value or waiving protections you genuinely need. Paying above market value, giving up inspection rights, or agreeing to an unrealistic deadline can create problems later. A competitive offer should be strong, not reckless.

Contract Clauses That Deserve Careful Attention

The exact language in a purchase agreement matters. A home-sale contingency can include deadlines for listing your property, accepting an offer, completing inspections, obtaining your buyer’s financing commitment, or closing. Each date should be achievable based on your property’s condition and local market activity.

Many contingent contracts also contain a kick-out clause, sometimes called a right-to-continue-marketing provision. This allows the seller to keep showing the home and accept another offer as a backup. If the seller receives a better or non-contingent offer, you may be given a limited period to remove your contingency or step aside.

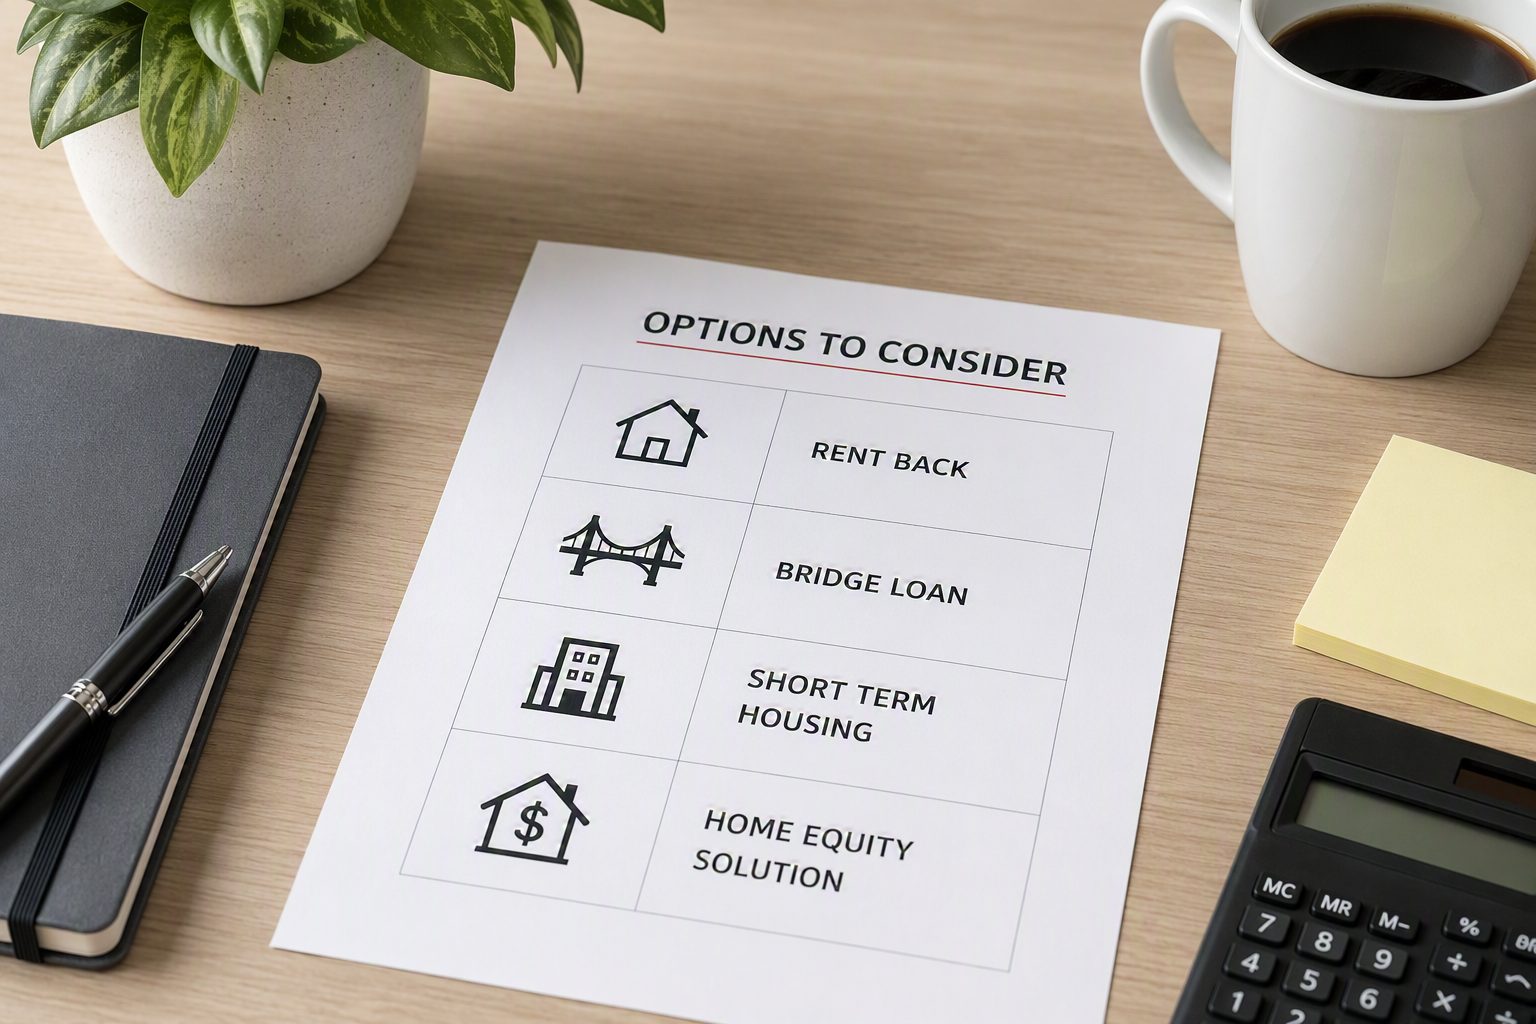
That deadline can be stressful, but it serves a purpose. It gives the seller a path forward while giving you an opportunity to decide whether you can proceed without the sale of your current home. Before agreeing to this type of clause, talk with your lender about whether a bridge loan, home equity option, or other financing approach is truly available and affordable. Do not assume you can remove the contingency later without a clear plan.

Also pay attention to the difference between a contingency based on selling your home and one based on closing the sale. If your home goes under contract but the buyer later cannot obtain financing, your purchase could still be affected. The more details you understand upfront, the fewer surprises you are likely to face after inspections begin.

Alternatives When Timing Is Tight

Sometimes a traditional contingency is the best choice. Other times, a different plan may better fit your finances and the competition for the homes you are considering.

You might sell your current home first and negotiate a longer closing date or temporary post-closing possession, if the buyer agrees. This can provide more certainty, though it may require flexibility if you have not found your next home. Another option is to make a non-contingent offer only after confirming with your lender that you can safely qualify and carry the costs involved. Some homeowners explore bridge financing or a home equity line, but those tools involve interest costs, qualification requirements, and meaningful risk if the home takes longer to sell.

For certain buyers, selling first and renting briefly is the least emotionally appealing option but the strongest financial one. It removes the sale contingency from your next offer and may place you in a more competitive position. Whether that trade-off is worthwhile depends on your budget, moving needs, pets, school schedule, and comfort with a temporary move.

Start With a Plan for Both Homes

Buying and selling at the same time involves more than matching two closing dates. You need a clear estimate of your equity, a pricing plan for your current property, a lender conversation about multiple scenarios, and a realistic understanding of the type of homes you want to pursue.

A personalized strategy is especially valuable when your move involves different markets across Northern Kentucky and Greater Cincinnati. The pace of sales, price ranges, and buyer expectations can vary from one neighborhood to the next. Working through those details before the right home appears helps you act confidently instead of making a rushed decision under pressure.

The best next step is not always to list immediately or write an offer immediately. It is to understand your choices well enough that, when the right home comes along, your move supports the life you are building rather than stretching your finances too thin.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080
Real Estate Market • July 20, 2026

Buying a House in Northern Kentucky Made Clear

A home search can start with a saved listing, but buying a house in Northern Kentucky becomes real when you begin weighing commute times, school routines, monthly payments, and the kind of life you want to build. One neighborhood may offer a walkable town center and older homes with character; another may offer newer construction, more space, or quicker access to downtown Cincinnati. The right choice is personal, and a thoughtful plan helps make a major decision feel far more manageable.

Start With the Life You Want at Home

Before looking closely at individual properties, get clear about what needs to work for your household. A three-bedroom home may look perfect online, but its storage, lot layout, stairs, traffic pattern, and location can tell a different story in person. Think about your non-negotiables, your preferences, and the items you may be willing to change later.

For some buyers, the priority is a short drive to work in Cincinnati or a convenient airport route. For others, it is a larger yard, proximity to parks, a particular school district, or a neighborhood where friends and family are close by. Northern Kentucky offers a wide mix of communities and housing styles, from historic homes in places such as Covington and Newport to suburban neighborhoods in Fort Mitchell, Florence, Independence, Union, and beyond.

Try to avoid treating every item as equally important. You can update paint, flooring, or light fixtures. Changing a home’s location, lot, or daily commute is much harder. A buyer consultation can help turn a broad wish list into a clear search strategy before the first showing.


Get Comfortable With Your Full Monthly Budget

The purchase price matters, but it is not the only number that belongs in your decision. A comfortable monthly housing payment should account for principal and interest, property taxes, homeowners insurance, and, when applicable, private mortgage insurance or homeowners association dues. Your lender can explain how each factor affects your estimated payment and how different loan programs may fit your situation.

Closing costs also deserve attention early. These can include lender charges, title-related costs, prepaid insurance, tax escrows, appraisal fees, and other transaction expenses. The exact amount varies by loan, property, and contract terms, so a reliable estimate from your lender gives you a more accurate picture than relying on a general rule of thumb.

Leave room for life after closing, too. Even a well-maintained home may need a new appliance, a service call, window coverings, moving help, or a project you choose to tackle once you move in. Buying at the top of an approved loan amount can be right for some households, but approval is different from comfort. The goal is a home payment that supports your life rather than limiting it.

Choose a Lender Before the Search Gets Serious

A preapproval is more than a box to check. It gives you a defined price range, lets you move quickly when the right property appears, and shows sellers that you have taken the financing side seriously. In a competitive situation, that confidence can matter.

Ask a lender to explain the difference between the interest rate, annual percentage rate, estimated cash to close, and the monthly payment at several price points. If you are comparing loan options, consider the down payment, mortgage insurance, rate, and how long you expect to own the home. A lower down payment can preserve cash for repairs and reserves, while a larger down payment may reduce the loan amount or monthly costs. Neither approach is automatically better.

It is also wise to protect your credit and avoid major financial changes while under contract. Opening new credit accounts, financing furniture, changing jobs, or moving money without documentation can create delays during underwriting. When in doubt, ask your lender before making a financial move.

Buying a House in Northern Kentucky Means Comparing Communities

Online research is useful, but it cannot replace spending time in the areas you are considering. Visit at different times of day. Drive the route to work. Notice how long errands take, where you would walk the dog, and whether the streets feel like a fit for your household. A Saturday afternoon can reveal something entirely different from a weekday morning.

Property taxes, school district boundaries, utility providers, zoning, and homeowners association rules can vary from one community to the next. If a home is near a commercial corridor, a busy road, a floodplain, or an area of planned development, ask questions rather than making assumptions. These details do not make a property good or bad, but they can affect daily living, insurance, resale considerations, and your comfort level.

For buyers relocating from across the river or farther away, local perspective can save time. Kory Freudenberg of Sibcy Cline Realtors can help you compare homes in the context of the surrounding community, not just by square footage and bedroom count.

Look Beyond the Cosmetic First Impression

A bright kitchen or beautifully staged living room can make a home easy to love. Still, the most important features are often less visible. During showings, pay attention to the age and apparent condition of the roof, HVAC system, windows, foundation, drainage, electrical panel, and water heater. Look for signs of moisture, cracks, uneven floors, or repairs that deserve a closer look.

This is not about trying to inspect a house on your own. It is about recognizing where questions may be needed. A seller’s disclosure can provide helpful background, but it should be read alongside your own observations and professional inspections. Older homes can offer craftsmanship and charm, while newer homes may offer more modern layouts and systems. Each comes with different maintenance expectations.

Consider the property as a whole. A home needing updates may be a strong opportunity if the location, structure, and price align with your plans. On the other hand, a move-in-ready home may justify a higher price if it reduces the time, expense, and disruption of renovations. The best fit depends on your budget, schedule, skills, and appetite for projects.

Make an Offer With Strategy, Not Panic

When you find a home that feels right, a strong offer is about more than offering the highest number. Price matters, but sellers may also consider financing strength, earnest money, inspection terms, requested closing date, appraisal considerations, and contingencies. The goal is to write an offer that protects your interests while responding to the property’s market position.

A comparative market analysis can help you understand recent nearby sales, current competition, and the home’s likely value range. No two properties are identical, especially in neighborhoods with varying lot sizes, updates, and home ages. Still, good market data keeps emotion from taking over the decision.

Be careful with strategies that remove protections simply to make an offer more appealing. Waiving or shortening contingencies can carry real risk. There are circumstances where buyers make those choices knowingly, but they should understand the financial implications first. A personalized conversation about the home, your financing, and your goals is more useful than a one-size-fits-all offer formula.

Use the Inspection Period Well

Once a contract is accepted, the inspection period is a time for due diligence, not a reason to expect a perfect report. Nearly every house, including a newer one, will have maintenance items and recommendations. A qualified home inspector can help identify material concerns and give you a clearer understanding of the property.

Focus on health and safety concerns, structural issues, expensive systems near the end of their useful life, and problems that could affect your ability to insure or finance the home. Smaller items can still be useful for planning, but asking a seller to repair every issue can distract from what truly matters.

Depending on the property, additional evaluations may be appropriate for radon, sewer lines, chimneys, pests, or specialized systems. Your agent can help coordinate the timeline and explain available options if an inspection reveals something unexpected. The right response may be a repair request, a credit, a price adjustment, further investigation, or occasionally a decision to walk away under the contract terms.

Keep Closing Day on Track

After inspections and negotiations, stay responsive to your lender, agent, title company, and insurance provider. Provide requested documents promptly and review estimates carefully. Before closing, you will typically complete a final walkthrough to confirm the property is in the agreed-upon condition and that any negotiated work has been addressed.

A little organization makes this period easier. Keep your important documents in one place, confirm utility transfer details, and avoid last-minute purchases that could affect your loan approval. Closing day is exciting, but the work behind it is what creates confidence when you receive the keys.

The right home is not always the most polished one or the one that creates the biggest rush of excitement at a showing. It is the home that fits your financial comfort, your everyday needs, and the next chapter you are ready to begin. With local guidance and a plan built around your priorities, you can move forward with clarity and enjoy the moment the house finally starts to feel like home.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080
Real Estate Tips • July 17, 2026

The Best Home Improvements Before Selling

As a seller, you may be tempted to renovate every outdated room before listing. But the best home improvements before selling are rarely the biggest or most expensive projects. They are the updates that help buyers feel confident from the moment they pull up, while keeping your time, budget, and likely sale price in balance.

The goal is not to create your dream home for someone else. It is to present a well-cared-for property that makes it easy for buyers to picture their own next chapter there. In the Cincinnati Tri-State market, that usually means prioritizing condition, cleanliness, and first impressions over highly personal upgrades.

Start With What Buyers Will Notice First

Before selecting paint colors or shopping for new fixtures, address anything that suggests the home has not been maintained. Buyers can live with an older kitchen more easily than they can live with questions about a leaking roof, a damp basement, or an HVAC system that seems unreliable.

A pre-listing walkthrough can help separate true concerns from cosmetic imperfections. Look for loose railings, cracked exterior caulk, damaged gutters, peeling paint, dripping faucets, sticking doors, and burned-out light bulbs. None of these projects may feel exciting, but together they signal that the house has been cared for.

If you know of a larger issue, it is often better to understand it before a buyer’s inspection does. The right response depends on the repair, the home’s price range, and current local buyer demand. Sometimes repairing the issue is the clearest path. Other times, disclosing it and pricing accordingly makes more financial sense. A personalized pricing and preparation conversation can keep you from spending money in the wrong place.

Best Home Improvements Before Selling: Focus on First Impressions

Curb appeal has an outsized effect because buyers begin forming opinions before they reach the front door. You do not need a landscape overhaul. A tidy, welcoming exterior is usually enough to set the right tone.

Freshen the front entry with a clean door, updated hardware if needed, a working porch light, and a simple seasonal container or two. Pressure-wash siding, walkways, and the porch when appropriate. Trim overgrown shrubs, remove dead plants, edge the beds, and make sure house numbers are easy to see. If the exterior paint is peeling or the front door looks tired, targeted painting can be one of the most visible improvements you make.

Northern Kentucky weather can be hard on outdoor surfaces. Pay close attention to wood rot, loose steps, cracked concrete that creates a trip hazard, and gutters pulling away from the home. These details affect both appearance and buyer confidence.

Paint Is Often the Highest-Value Cosmetic Update

A fresh coat of paint can change the feeling of a home more than many larger projects. It makes rooms appear cleaner, brighter, and better maintained. Neutral does not have to mean bland, but it should help buyers focus on the room rather than a bold personal color choice.

Prioritize high-traffic areas, entryways, hallways, kitchens, and bedrooms with scuffs or strong colors. Repair nail holes, patch damaged drywall, and touch up trim at the same time. Consistency matters. A home with clean walls and crisp trim feels more move-in ready, even when it has not been fully renovated.

Avoid painting every surface simply because it is old. If the current color is light, clean, and broadly appealing, spending that money elsewhere may be wiser. The same is true for specialty finishes. Buyers may appreciate quality, but they should not have to work hard to imagine changing the room.

Make the Kitchen and Bathrooms Feel Clean and Functional

Kitchens and bathrooms influence buyer perception, but full remodels before selling can be risky. You may spend heavily on finishes that do not match the eventual buyer’s taste, especially if nearby homes do not support a higher sale price.

Instead, begin with practical improvements. Deep-clean cabinets, grout, appliances, exhaust fans, and fixtures. Replace worn caulk around tubs and sinks. Fix slow drains, leaks, loose handles, and cabinet doors that do not close properly. Clear countertops so buyers can see the available workspace.

If cabinets are structurally sound but dated, professional painting, new hardware, and improved lighting can give the room a meaningful lift at a fraction of the cost of replacement. In some homes, replacing a visibly worn countertop or an outdated faucet is worthwhile. The decision should be based on what competing listings offer and what buyers in your price point expect.

Improve Light, Flooring, and Everyday Comfort

Dark rooms and worn flooring can make buyers assume a house needs more work than it actually does. Start by opening blinds, washing windows, replacing burnt-out bulbs, and using consistent warm-white lighting throughout the home. Remove heavy window treatments if they block natural light or make rooms feel smaller.

For flooring, a professional cleaning may be enough for carpet that is in good condition. Replace carpet with stains, strong odors, or significant wear, particularly in main living areas and bedrooms. Refinish hardwood floors when they are a true selling feature and the condition warrants it. If several flooring types meet awkwardly from room to room, a more unified look can help, but only if the expected return supports the cost.

Comfort details also matter. Service the HVAC system, make sure vents are unobstructed, and replace an obviously aging thermostat if it is unreliable. Buyers do not expect every system to be brand new. They do want evidence that the home has been maintained responsibly.

Do Not Over-Improve for the Neighborhood

One of the most common seller mistakes is treating resale preparation like a long-term renovation plan. A luxury kitchen, premium landscaping, or custom feature may be beautiful, but it does not always translate into a comparable increase in sale price.

Before committing to a major project, consider four questions:

  • Will this repair remove a buyer objection or inspection concern?
  • Will it improve photos, showings, or first impressions?
  • Do similar homes nearby offer this feature or level of finish?
  • Could the money be better used for pricing, preparation, or your next move?

An older home can sell very well when it is clean, honest, and appropriately priced. Buyers often prefer the chance to personalize finishes themselves. What they are less willing to take on are deferred maintenance issues, unpleasant odors, clutter, or uncertainty about the home’s condition.

Prepare the Home So Improvements Can Be Seen

Even thoughtful updates lose impact in a crowded or overly personalized space. Decluttering is not just a staging task. It helps rooms look larger, highlights storage, and lets buyers focus on the house rather than the belongings inside it.

Pack away excess furniture, family photos, collections, and off-season items. Clean closets and cabinets because buyers will open them. Address pet odors, cooking odors, smoke odors, and damp basement smells directly rather than covering them with strong fragrances. A clean, neutral-smelling home feels more welcoming and more trustworthy.

Professional photos should happen after repairs, cleaning, and simple staging are complete. The first showing frequently begins online, so the condition you create in person needs to come through in the listing photos as well.

Let the Local Market Guide the Final Decisions

There is no universal renovation checklist that fits every seller. A well-maintained ranch in Fort Thomas, a historic home in Covington, and a newer family home in Independence can each call for a different strategy. Price point, competing inventory, buyer expectations, and your timeline all matter.

Before you start writing checks, walk through the home with a local real estate professional who can help identify what buyers are likely to notice and what is unlikely to pay back. The right plan is not about making your house perfect. It is about helping the right buyer see its value clearly and move forward with confidence.

Reach out today.  Your Home is My Purpose.  Guiding You Like Family. Advising You Like a Professional. 859-640-6080